Last Updated 2 hours ago by Kenya Engineer
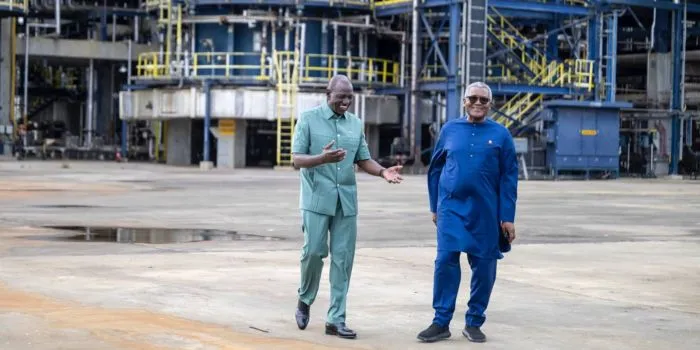
When Aliko Dangote’s proposed oil refinery in Lamu breaks ground, Kenya will be taking a very large bet on the future of East Africa’s petroleum industry.
The planned facility is expected to have a crude-processing capacity of 700,000 barrels per day, making it one of the largest refineries in Africa and considerably larger than Kenya’s historical domestic petroleum market. Dangote Industries expects the project to cost between US$15 billion and US$16 billion, with construction targeted for completion around 2030. Engineers India Limited has already secured a contract of more than US$450 million to provide project-management and engineering, procurement and construction-management services for the greenfield refinery and petrochemical complex.
The scale is striking. Kenya’s total domestic petroleum demand reached about 5.7 million tonnes in 2025, with diesel and petrol accounting for more than 70 per cent of consumption. A 700,000-barrel-per-day refinery, by comparison, would process roughly 255 million barrels of crude a year if operated continuously. The Lamu project therefore cannot economically be regarded simply as a facility intended to replace Kenya’s imports. Its business model must be regional and, potentially, global.
What exactly is being built?
The publicly available information describes the Lamu project as a 700,000-barrel-per-day greenfield refinery and petrochemical complex located within the LAPSSET special economic zone near the Port of Lamu.
Beyond that headline capacity, however, the detailed engineering configuration has not yet been publicly disclosed in the way that the specifications of Dangote’s Nigerian refinery have been.
Dangote’s existing Nigerian facility provides a useful indication of the kind of industrial platform the company may be seeking to reproduce in Kenya. Its Nigerian refinery is a 700,000-bpd single-train facility, with a high-complexity configuration, integrated storage, pipelines, marine infrastructure, independent power generation and petrochemical production. It produces products including petrol, diesel, aviation fuel and LPG, while its associated petrochemical facilities produce polypropylene. The Nigerian refinery is designed to produce fuels to Euro V specifications.
It would be premature, however, to assume that every one of those specifications will be duplicated at Lamu. The Kenyan project is still at the development and engineering stage, and its publicly confirmed technical specification remains principally its 700,000-bpd processing capacity and its integration into a petrochemical complex.
Its location nevertheless gives it one major advantage: access to the Indian Ocean.
The refinery can potentially receive crude by tanker rather than depending entirely on a single regional pipeline. That flexibility may prove crucial during its early years.
The 700,000-barrel question
The most important question about Lamu is whether it can be fed economically.
A refinery is not normally designed around running at its nameplate capacity every day of the year. Maintenance, equipment availability, crude quality and market conditions all affect utilisation. At 85 per cent utilisation, a 700,000-bpd refinery would require about 595,000 barrels of crude every day. At 90 per cent, it would require approximately 630,000 barrels per day.
That immediately creates a feedstock challenge for East Africa.
Kenya is only now approaching commercial oil production. The South Lokichar development is expected to begin at around 20,000 barrels per day and eventually reach approximately 120,000 barrels per day by 2032. The crude would require an approximately 825-kilometre pipeline to Lamu under the current development concept.
Uganda is much more significant. The Tilenga and Kingfisher developments are expected to reach approximately 230,000 barrels per day at plateau, with around 1.4 billion barrels of crude expected to be produced over at least 20 years. Uganda’s crude is, however, already committed to a very different infrastructure strategy: the 1,443-kilometre East African Crude Oil Pipeline carries it southwards to the Tanzanian port of Tanga.
South Sudan presents another potentially substantial source. Before the current disruption of its export system, the country was producing around 150,000 barrels per day. In June 2026, however, South Sudan’s production was reported at only about 60,000–65,000 barrels per day, after problems on the pipeline through Sudan prevented the export of its Dar Blend crude. Its Nile Blend exports have continued through a separate route.
Kenya, Uganda and South Sudan therefore possess enough petroleum resources collectively to make a regional refinery concept plausible over the long term.
But that does not mean 600,000 barrels per day will automatically arrive at Lamu.
And what about the DRC?
The Democratic Republic of Congo is frequently mentioned in the political vision for an East African regional refinery, but its current contribution needs to be put into perspective.
The DRC is an oil producer, but its present production is tiny compared with Uganda’s future output. Available production data put current Congolese crude production at roughly 16,000 barrels per day, down from around 25,000 barrels per day several years ago. Its existing coastal production is exported.
The DRC therefore represents more of a future regional opportunity than the feedstock solution for a 700,000-bpd Lamu refinery today.
Its importance could grow if exploration around the country’s eastern basins, including areas associated with the Albertine Rift, eventually produces commercially significant volumes. But those barrels should not be counted as guaranteed refinery feedstock until the discoveries, development plans, pipelines and commercial agreements actually exist.
The Tanga alternative
This is where the Lamu story becomes much more interesting.
Earlier this year, the East African conversation appeared to be moving towards a joint refinery at Tanga.
In April, President William Ruto said Kenya, Tanzania, Uganda, South Sudan and the DRC were discussing a common refinery at Tanga, and Dangote said he was prepared to lead its construction if governments provided the necessary support. The concept was compelling because Tanga already sits at the end of EACOP, the infrastructure being built specifically to move Uganda’s crude to the Indian Ocean.
The Tanga proposition therefore had an obvious technical logic.
Ugandan crude would arrive at Tanga through EACOP. A refinery could be located close to that crude supply and to the marine export terminal. Refined products could then move inland towards Uganda and other East African markets, while additional crude could be imported or brought in from other regional producers.
But the regional refinery concept did not become the Dangote project.
By July, Dangote’s proposed location had moved first towards Kenya’s coast and ultimately to Lamu, while Tanzania and Uganda continued developing their own energy infrastructure strategy.
The reasons appear to be partly commercial and partly infrastructural.
Lamu offers a deep-water port and a strategic position at the northern end of the LAPSSET corridor. Kenya also has the larger established petroleum-product distribution system and a substantial domestic market. Most importantly, a Lamu refinery can be designed from the beginning as a seaborne merchant refinery, importing crude when regional supply is unavailable and exporting finished products when necessary.
That flexibility may be worth more to a private investor than dependence upon a single regional crude system.
But Tanga did not go away
In August, Uganda and Tanzania effectively revived the Tanga concept in a different form.
Uganda’s UNOC, Tanzania’s TPDC and Vitol Bahrain signed an MoU to develop a Tanga Regional Energy Hub incorporating petroleum storage, logistics, trading and distribution infrastructure, together with a proposed refinery. The project builds directly on EACOP and is intended to complement Uganda’s own planned Hoima refinery.
This produces an intriguing situation.
East Africa could ultimately have three interconnected refining propositions: Uganda’s 60,000-bpd Hoima refinery, the proposed Tanga refinery and Dangote’s 700,000-bpd Lamu refinery.
Uganda’s refinery is particularly important because Uganda’s commercialisation strategy has always envisaged both domestic refining and crude exports. Uganda plans a refinery at Kabaale with an eventual input capacity of 60,000 barrels per day, while EACOP provides an export route for crude to Tanga. Uganda’s own petroleum authority says the refinery is intended to have first call on Ugandan crude when both projects are operating.
That means Lamu cannot simply assume that Uganda’s entire 230,000-bpd plateau production will be available to it.
So where will Lamu’s optimum crude come from?
At least initially, the answer may be the international market.
This is perhaps the least appreciated part of the project.
A refinery at Lamu does not necessarily need East African crude to survive. It needs competitively priced crude with the right chemical characteristics, reliable shipping access and a product market capable of absorbing its output.
Lamu’s ocean location makes that possible. Tankers could bring crude from the Middle East, West Africa or other producing regions while East African production develops.
The problem is that importing crude while simultaneously trying to compete against refineries located closer to major crude sources introduces additional freight and working-capital costs.
This is exactly why the experience of Dangote’s Nigerian refinery is instructive. Even Nigeria’s giant refinery, sitting inside one of Africa’s largest oil-producing countries, has faced crude-supply challenges and has had to import a significant portion of its crude feedstock. Its coastal location has nevertheless provided the flexibility to source internationally.
For Lamu, the optimum operating model may eventually be a blend:
Kenyan crude when Lokichar reaches commercial production; selected Ugandan or South Sudanese crude if commercially available; other regional barrels where pipeline economics make sense; and imported seaborne crude to fill the balance.
Does the refinery make economic sense for Kenya?
There are two different questions here.
Does a 700,000-bpd refinery make sense purely for Kenya’s domestic market?
Clearly, the scale would be difficult to justify on that basis alone.
Does a 700,000-bpd merchant refinery make sense if Lamu becomes a regional petroleum-processing and export hub?
That is a much more credible proposition.
Kenya currently imports essentially all of its petroleum requirements, while domestic demand continues to grow. In 2025, net petroleum-fuel imports were about 4.5 million tonnes, while total domestic demand reached 5.7 million tonnes.
A successful refinery could therefore capture value currently leaving the region in the form of imported refined products.
It could also create a much larger industrial ecosystem around Lamu: crude storage, product storage, marine services, pipelines, power generation, petrochemicals, packaging, chemicals, engineering services, logistics and export infrastructure.
The government expects the project and associated development to create tens of thousands of jobs. More importantly, the economic value would not necessarily come from the refinery’s direct employment alone. It would come from the industrial cluster built around it.
There is, however, a significant caveat. Kenya must avoid building a refinery whose economics depend upon permanently subsidised crude, guaranteed government offtake or politically protected product prices.
The strongest case for Lamu is not that Kenya needs a refinery. It is that East Africa may need a large coastal merchant refinery, and Lamu could potentially become the location from which that refinery serves the region and international markets.
The real test
The first test will be crude.
At 85 per cent utilisation, Dangote’s Lamu refinery would need nearly 600,000 barrels every day. East Africa’s potential production can eventually approach that level, but the barrels are spread across different countries, different ownership structures and different export systems.
Uganda’s crude is heading towards Tanga. South Sudan’s crude is constrained by its dependence on Sudanese export infrastructure. Kenya’s production is only beginning. The DRC’s present output is comparatively small. And Tanzania itself is still developing its position as an energy hub.
The second test will be the market.
A refinery this large must sell enormous volumes of diesel, petrol, jet fuel, LPG and other products. Kenya alone cannot absorb them. Uganda, Tanzania, Rwanda, Burundi, South Sudan, eastern DRC, Ethiopia and potentially markets farther afield would have to become part of the commercial equation.
The third test will be infrastructure.
Lamu currently has only three completed berths, while the broader LAPSSET vision requires a much larger port, storage facilities, pipelines and inland transport links. The proposed refinery therefore depends partly on infrastructure that is still being developed.
And finally there is the question of regional coordination.
The irony is that the original East African argument for a Tanga refinery remains valid even though Dangote is now pursuing Lamu. Uganda has the crude. Kenya has a large downstream market and Lamu’s deep-water location. Tanzania has EACOP’s marine terminus and Tanga’s emerging energy hub. South Sudan has potentially large crude resources but needs an alternative export route. The DRC has longer-term resource potential and large markets.
In theory, these assets complement one another. In practice, pipelines, national interests, refinery ownership, crude contracts, tariffs and geopolitics determine where the barrels actually flow.
That may ultimately decide whether Lamu’s 700,000 barrels per day becomes the foundation of a new East African petroleum industry.
-
Product on sale
 AWEBook Volume 2Original price was: KShs 3,500.00.KShs 3,000.00Current price is: KShs 3,000.00.