Last Updated 1 day ago by Kenya Engineer
For years, Nairobi City County and Kenya Power have periodically found themselves on opposite sides of the same electricity bill.
The disagreements have ranged from unpaid electricity bills to wayleave charges, street lighting costs and, at times, the threat or actual interruption of electricity services. In 2025, the two sides were publicly disputing billions of shillings in electricity and wayleave-related claims. A parliamentary record subsequently put the reconciled electricity debt at about KSh1.8 billion, with approximately KSh1.5 billion attributed to street lighting. The dispute was not merely an accounting disagreement. It exposed the extent to which a major city government can become financially and operationally dependent on a utility over which it has little influence.
The relationship became more complicated in 2026 when the High Court considered a dispute arising from the disconnection of county facilities and found that the applicable intergovernmental dispute-resolution mechanisms should have been exhausted before essential county services were disconnected.
These disputes raise a larger question than who owes whom. Could Nairobi County change the way it buys, manages and ultimately supplies electricity?
The question would have sounded unrealistic a decade ago. It is considerably less so today.
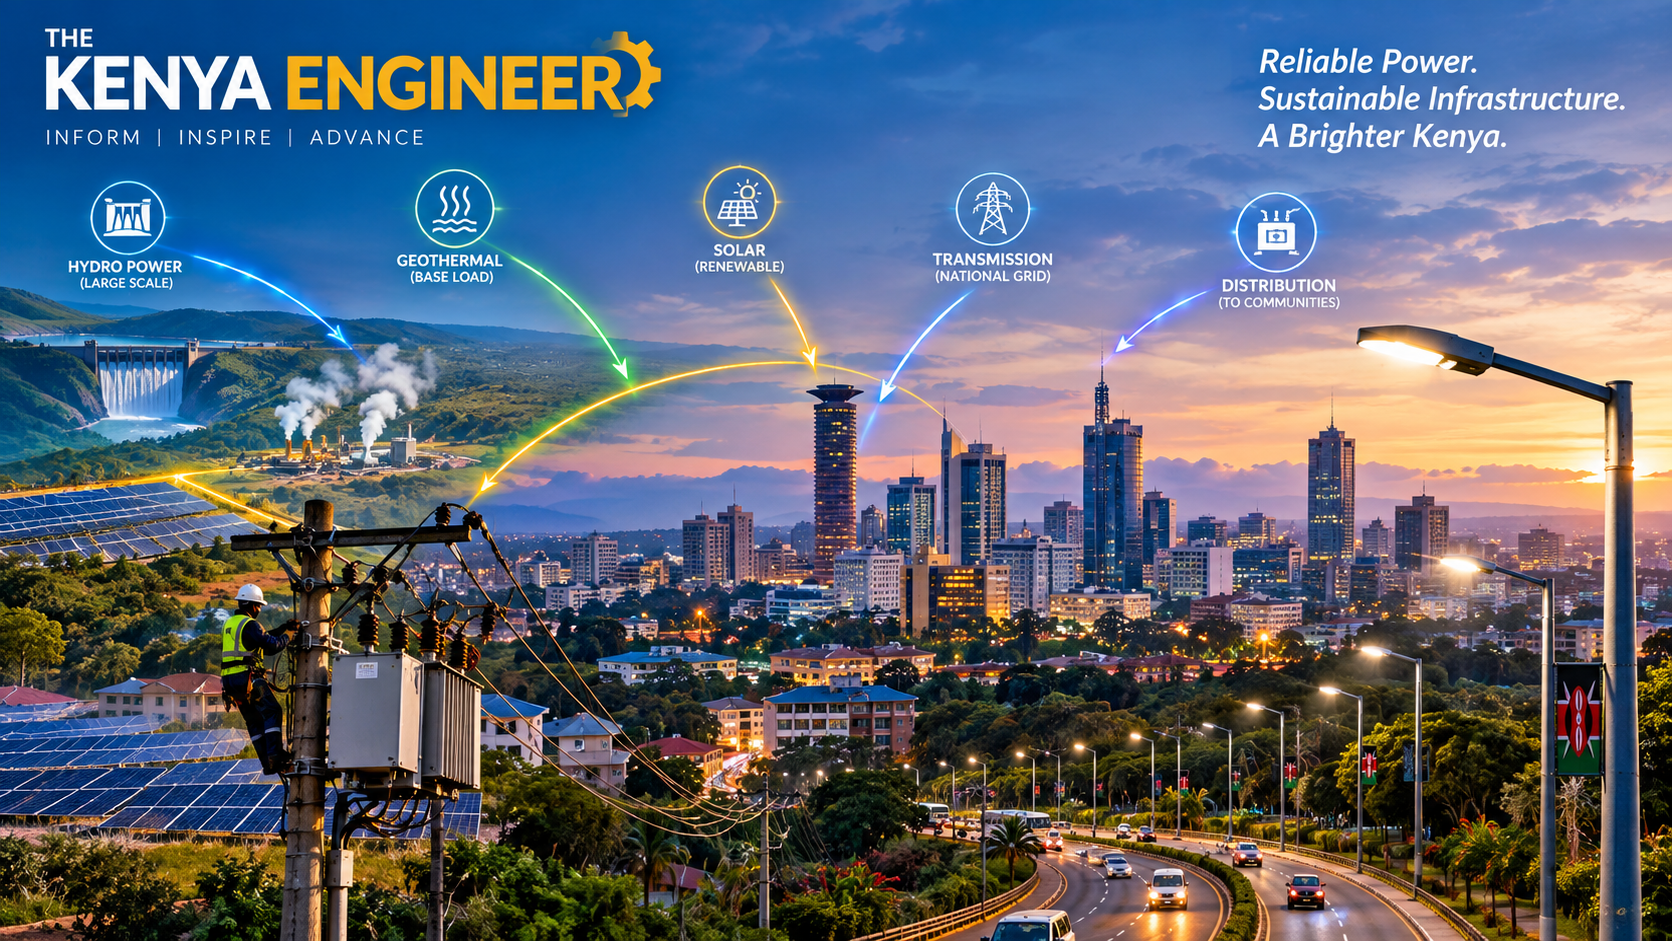
Kenya’s electricity sector is moving away from a model in which electricity consumers overwhelmingly buy their electricity from one dominant distributor and toward a market in which generation, wholesale supply, network services and retail supply are increasingly capable of being separated.
The change has been gradual. The Energy Act, 2019 provided much of the statutory foundation. The Energy (Electricity Market, Bulk Supply and Open Access) Regulations, 2024 attempted to establish the machinery for a more competitive market. In May 2026, the Government gazetted a new set of Energy (Electricity Market, Bulk Supply and Open Access) Regulations, replacing the 2024 framework and taking the open-access model further. EPRA now lists the 2026 regulations among the current electricity regulatory instruments.
This does not mean that Kenya Power has suddenly ceased to be the dominant electricity distributor. It remains the country’s overwhelmingly established distribution and retail utility, with an extensive network, millions of customers and decades of accumulated infrastructure.
But a dominant incumbent is not the same thing as a permanent legal monopoly. That distinction could become increasingly important for Nairobi.
The law has been moving towards competition
The Energy Act, 2019 created separate licensing categories covering generation, transmission, distribution and retail supply. The Act gives the Energy and Petroleum Regulatory Authority responsibility for regulating the generation, importation, exportation, transmission, distribution, supply and use of electrical energy.
It also provides for retail licences covering particular areas or areas of supply. The legislation therefore does not reserve the retail supply of electricity exclusively to Kenya Power.
The Act’s framework is particularly significant because it recognises retail supply as an activity that can be licensed separately from distribution.
The 2024 Electricity Market, Bulk Supply and Open Access Regulations gave this principle a practical framework. Among other provisions, they contemplated multiple suppliers, bulk supply contracts between licensees, open access to transmission and distribution networks, and wheeling arrangements. The regulations also provided for a consumer to choose a retail supplier, subject to the rules governing existing supply contracts.
The 2024 framework was nevertheless incomplete from the perspective of an ordinary household. Existing Kenya Power customers could not simply abandon their existing supply contracts and sign up with a competing retailer overnight. The regulations were an important step towards competition, but the practical transition remained limited.
The 2026 regulations are more consequential.
They establish a more developed electricity market framework involving generators, network service providers, retailers, consumers and eligible consumers. They provide mechanisms for electricity to move across existing networks under open-access arrangements and enable eligible consumers to procure electricity from generators other than the incumbent supplier, subject to the regulatory and contractual requirements of the market.
The threshold for an eligible consumer is particularly relevant to large organisations. Current reporting on the 2026 framework identifies the threshold as at least 1 MVA at distribution level or 10 MVA at transmission level.
For Nairobi County, that should prompt a serious question.
How much electricity does the county itself consume across its hospitals, offices, water and sewerage facilities, markets, street lighting, depots, public facilities and other infrastructure?
If its aggregated demand is sufficiently large, Nairobi does not necessarily need to begin by persuading hundreds of thousands of residents to change electricity suppliers. It could begin by becoming a sophisticated electricity buyer for itself.
Nairobi does not have to build another Kenya Power
The phrase “Nairobi electricity utility” might immediately conjure up images of thousands of kilometres of new power lines, substations, transformers and household connections.
That is not the proposal. At least, it should not be the first proposal.
Building a second electricity distribution network across Nairobi alongside Kenya Power’s existing network would make little economic sense in most parts of the city. Electricity distribution is a network business, and duplicating poles, transformers and cables along the same roads simply to create competition would waste capital.
Competition can instead take place at several different layers.
Nairobi could become a licensed electricity retailer and power procurement entity. It could purchase electricity from licensed generators and supply its own facilities, subject to the applicable market and network arrangements. Where the national grid is used, the utility would pay the regulated charges associated with transmission, distribution or wheeling.
The physical electrons would still travel through the national electricity system. The difference would be who purchased them and who sold them to the final customer.
This is already reflected in the architecture of Kenya’s emerging electricity market. The 2024 regulations contemplated bulk supply contracts between licensees, open-access applications and wheeling service agreements. The 2026 regulations replace that framework with a more developed market regime.
For Nairobi, that creates an opportunity to separate three questions which have traditionally been treated almost as one. Who generates the electricity? Who owns the network? 1Who sells the electricity to the customer?
They do not necessarily have to be the same entity.
Nairobi could start with the customer it already owns
The most compelling argument for a Nairobi electricity utility is not initially the 5 million or more people living and working in the city.
It is Nairobi County itself. The county is already a large electricity consumer.
Its facilities include administrative buildings, health facilities, markets, workshops, water and wastewater infrastructure, public amenities, street lighting and other electricity-intensive installations.
Street lighting alone represents a substantial electricity load and has been at the centre of Nairobi’s disputes with Kenya Power.
This creates the possibility of an anchor-customer model. A county-owned utility could initially procure electricity primarily for county operations. Instead of Nairobi being merely a customer of Kenya Power, it would become an electricity market participant.
It could assess offers from different licensed generators, negotiate power supply contracts where permitted, combine grid electricity with solar generation and storage, and optimise the electricity consumption of its own facilities.
The county could then measure the financial result before expanding the business. If the experiment does not reduce the cost of electricity, the county would have learnt an important lesson without committing itself to an expensive citywide distribution network.
If it does reduce costs, Nairobi would have established the commercial case for expansion.
A utility built around Nairobi’s existing Energy and Lighting capability
There is another reason this proposal deserves consideration. Nairobi is not starting with an empty desk.
The Energy and Lighting Directorate already exists within the county government. It has personnel, technical divisions, vehicles, equipment and practical experience maintaining public lighting infrastructure.
Those capabilities should not be underestimated.
A modern electricity utility needs engineers, electricians, technicians, planners, procurement specialists, commercial managers, customer-service personnel, metering specialists, data analysts and network operations staff.
The existing Energy and Lighting function does not possess all of those capabilities in the form required for a licensed electricity retailer or distributor. It would need substantial strengthening.
But it does provide a technical nucleus.
The proposal would therefore be to undertake a feasibility assessment of transforming the existing function into, or placing it under, a professionally governed county-owned electricity utility.
The County Governments Act gives county governments considerable institutional flexibility. Section 6 provides that a county government may establish a company, firm or other body for delivering a particular service or carrying out a particular function.
The Public Finance Management Act and the Public Finance Management (County Governments) Regulations provide an additional framework for county corporations and county government-owned enterprises. The regulations recognise commercially oriented county enterprises and require a business case and feasibility assessment addressing financial viability, the need for the corporation, its relationship with the county’s mandate and medium-term plan, its effect on the county’s fiscal position and the county’s proposed investment.
This is important because a Nairobi electricity utility should not be created simply by renaming a directorate.
It should be established as a commercially accountable entity with a clear mandate, audited accounts, professional management, appropriate technical capacity and a board capable of operating an electricity business.
What would the proposed utility actually do?
A possible model could be built around five functions.
First, electricity procurement.
The utility would aggregate the county government’s electricity demand and procure electricity from licensed generators and other permitted market participants.
Second, retail supply.
Where permitted under its licence, it would sell electricity to county facilities and eventually to other customers.
Third, distributed generation.
The utility could develop or contract solar, battery storage and other distributed energy resources for suitable county facilities.
Fourth, municipal energy infrastructure.
It could develop selected mini-grids and local networks where a distributed system makes technical and economic sense.
Fifth, energy management.
It could manage the county’s electricity demand as a portfolio rather than treating every meter as an isolated bill.
That last function could ultimately become one of its most valuable capabilities.
The street-lighting network could become the first laboratory
Nairobi’s street lighting programme provides a particularly suitable starting point because the county already has operational responsibility for the infrastructure.
The proposed utility could gradually integrate street lighting into a wider energy-management platform.
Existing and new street lights could be fitted with smart controllers and meters. Consumption could be monitored remotely. Faults could be automatically reported. Maintenance could be prioritised according to actual network performance rather than waiting for residents to report failures.
Solarisation could continue at the same time. There is no contradiction between solarising street lighting and establishing a county electricity utility. Solarisation reduces the amount of electricity the county needs to purchase. A utility improves the way the remaining electricity is procured and managed.
The two strategies could therefore reinforce each other.
In some locations, the appropriate solution might be grid electricity. In others, solar and battery storage might make more sense. In a third category, a hybrid system could be preferable.
The utility’s job would be to determine the least-cost and most reliable combination.
Mini-grids provide another route
Kenya already has examples of private and development-based electricity networks operating under regulatory oversight.
Tatu City is one of the more prominent examples. Tatu City Power operates electricity distribution and supply infrastructure within the development, demonstrating that electricity distribution and supply need not always be performed by Kenya Power. The significance of the example is not that Nairobi can reproduce Tatu City’s model across the whole city. Tatu City is a relatively contained development with a defined customer base and a purpose-built network.
The lesson for Nairobi is narrower and more useful.
Where there is a defined load, a defined geographic area and a strong commercial case, a separately licensed electricity network can be viable.
Nairobi could therefore identify suitable municipal energy zones.
These might include large public markets, major health campuses, public housing developments, industrial areas, transport facilities or new developments where the county controls significant land and infrastructure.
A municipal mini-grid could combine solar generation, battery storage and grid supply, with the county utility providing the commercial and operational structure.
The network would be developed where it makes economic sense, rather than attempting to replace Kenya Power’s network everywhere.
What about selling electricity to residents?
This should be the second stage rather than the first.
Once the county utility has demonstrated that it can procure power, manage accounts, operate metering systems, collect revenue and maintain infrastructure, it could seek to supply customers outside the county government.
The emerging regulatory framework is designed to permit competition among electricity suppliers, subject to licensing and the market rules. This creates the possibility that a resident or business could eventually have a choice of electricity retailer while continuing to receive electricity through the same physical network.
The important principle should be consumer choice. Nairobi should not force residents away from Kenya Power.
If a county utility can offer a competitive price, reliable service, transparent billing or a better combination of electricity and distributed-energy services, customers should have a reason to choose it.
That would be competition rather than political displacement.
The financial case needs to be tested, not assumed
There is a tempting argument that Nairobi could simply buy electricity directly from generators, avoid Kenya Power’s margin and therefore obtain much cheaper electricity.
The reality is more complicated.
Buying directly from a generator does not eliminate the cost of the electricity network.
If electricity is transmitted or distributed through existing infrastructure, the relevant transmission, distribution, wheeling, system-operation and other regulated charges remain. There are also costs associated with balancing, metering, losses, ancillary services, market administration and other obligations.
The correct financial question is therefore not whether Nairobi can eliminate the electricity bill. It is whether Nairobi can reduce its all-in cost of electricity by changing its procurement and supply arrangements.
That calculation should include:
generation price;
transmission charges;
distribution or wheeling charges;
system and market charges;
losses;
taxes and levies;
metering;
billing and collection;
staff;
maintenance;
financing;
customer-service costs;
and the capital cost of any new infrastructure.
Only after those costs are modelled should the county decide whether the business is financially viable. The potential upside, however, extends beyond cost reduction.
If the county utility eventually supplies external customers, it could generate a commercial margin which could be reinvested in network expansion, renewable generation, energy efficiency and public lighting.
The electricity bill could gradually become an infrastructure investment mechanism rather than merely an expenditure item.
The regulatory pathway
Nairobi would need to approach the project as a regulated electricity undertaking, not simply as a county commercial venture.
The first step should be a detailed legal and regulatory feasibility study. That study should determine which licences are required for each proposed activity.
A retail-supply model would require the appropriate EPRA licence.
A distribution network would require a distribution licence.
Generation assets would require the appropriate generation approvals or licences depending on their scale and technology.
Mini-grid projects would need to comply with the applicable licensing, planning, environmental, technical and grid-interconnection requirements.
The 2024 Energy (Electric Power Undertaking Licensing) Regulations were developed to provide a more current framework for licensing electricity undertakings, including generation, transmission, distribution and retail supply. EPRA’s regulatory framework also continues to recognise the licensing requirements for electricity undertakings.
The county would also need to address procurement law, public finance requirements, environmental approvals, land and wayleave matters, construction standards, electrical safety, metering requirements, consumer protection and applicable technical standards.
The utility could not simply buy electricity from a generator because the county is a large customer. It would have to become a compliant participant in the electricity market.
Nairobi’s institutional challenge may be greater than its technical challenge
The greatest threat to this proposal may not be electricity engineering.
It may be governance.
A county utility handling billions of shillings in electricity procurement and potentially collecting revenue from thousands or millions of customers would be an attractive target for political interference.
That would have to be addressed from the beginning.
The utility should therefore have a professional board with expertise in electricity, engineering, finance, law, regulation, procurement and commercial management. Its financial accounts should be independently audited. Its procurement should be transparent. Its electricity purchases should be subject to appropriate commercial and regulatory controls. Its management should be measured against clearly defined performance indicators. Most importantly, county electricity bills should be paid on time.
It would be difficult for Nairobi to convince private generators to extend competitive power contracts if the utility inherited the county’s existing culture of delayed payment.
A financially disciplined municipal utility would therefore need to be established alongside the licensing application.
Kenya Power should not be treated as the enemy
There is a temptation to frame the proposal as Nairobi versus Kenya Power. That would be unnecessary and counterproductive.
Kenya Power has built and operates an enormous national distribution network. Nairobi’s proposed utility would depend on that network for much of its early development.
The more realistic future is one in which Kenya Power remains an important network operator and electricity market participant while other licensed retailers, distributors and generators enter the market.
Kenya’s open-access framework is built around precisely this kind of separation.
Competition does not require the destruction of the incumbent. It requires that other qualified participants be allowed to operate under transparent rules.
For Nairobi, this could eventually mean buying some electricity from Kenya Power, some directly from generators, some from renewable-energy projects and some from its own distributed generation assets.
The county utility would choose according to cost, reliability and contractual conditions. Kenya Power would remain a supplier and network partner where its services are competitive.
A realistic implementation plan
Nairobi should resist the temptation to launch a citywide electricity company immediately. A phased programme would be more credible.
Phase one: feasibility and market study
The county should commission an independent study to establish its actual electricity consumption profile. This should map every major electricity account owned or paid for by the county, including street lighting.
The study should establish maximum demand, annual consumption, load profiles, tariff categories, arrears, power quality, outages and the geographic location of major loads.
It should then model the cost of continuing with the current arrangement against several alternatives:
continued Kenya Power supply;
direct procurement by eligible county consumers;
retail supply through a county utility;
solar and storage;
and combinations of these models.
The result should be a bankable business case rather than a political proposal.
Phase two: establish the utility
Subject to the feasibility study, Nairobi should establish a county-owned electricity corporation or company under the applicable county government and public-finance framework.
The existing Energy and Lighting Directorate would provide part of the technical foundation, but the new entity would need additional commercial, regulatory, financial and customer-service capabilities.
Its first mandate should be deliberately narrow: procure and manage electricity for Nairobi County.
Phase three: secure regulatory approvals
The utility would engage EPRA to determine the appropriate licensing pathway.
It should seek the licence or licences corresponding to the activities it intends to undertake rather than applying for every possible licence at once.
If Nairobi qualifies as an eligible consumer for particular loads, those loads could potentially provide an early opportunity for direct procurement under the open-access framework.
Phase four: pilot direct procurement
The county should select a defined group of high-consumption facilities. These could include major hospitals, water and wastewater facilities, offices and street lighting.
A pilot should then compare the actual delivered cost against the existing procurement model. The pilot should run long enough to capture seasonal changes and should include network, market, metering and balancing charges.
Phase five: municipal distributed-energy projects
Once the procurement model is proven, Nairobi could develop selected solar-plus-storage installations and municipal mini-grids. These should be chosen on technical and financial merit. Not every county facility needs its own power station.
Phase six: voluntary retail supply
Only after the utility has demonstrated financial and operational competence should it begin offering electricity to external customers.
The first customers could be large commercial consumers within selected municipal energy zones.
Residential customers could follow as the regulatory framework, metering systems, billing systems and customer-protection arrangements mature.
Phase seven: selective distribution
Finally, where there is a strong economic case, the utility could seek distribution licences for defined areas rather than attempting to reproduce Kenya Power’s network across the whole city.
This could be particularly attractive in new developments, municipal housing projects, large public facilities and areas where the county is already investing heavily in infrastructure.
The opportunity extends beyond electricity
A successful municipal electricity utility could eventually become part of a much broader Nairobi energy platform. Street lighting could be connected to a smart lighting management system. Solar generation could be coordinated across county facilities. Battery storage could support critical public infrastructure. Electricity consumption could be monitored in real time. Water pumping could be optimised against electricity prices. Public buildings could participate in demand management. Electric-vehicle charging could become part of the municipal electricity business. And the county could begin treating energy data as infrastructure information rather than merely a collection of monthly bills.
For a city attempting to become a regional technology, financial and commercial centre, this would be an important capability.
There is no guarantee that Nairobi electricity would be cheaper
That caveat should remain at the heart of the proposal. A county-owned electricity utility could fail. It could become another poorly managed public enterprise. It could accumulate debts. It could suffer political interference. Its procurement costs could be higher than Kenya Power’s. Its customer collection could be poor. Its network could require more capital than the county can afford. Its regulatory obligations could make the business unattractive.
These are not reasons to dismiss the idea.
They are reasons to subject it to a rigorous feasibility study before committing public money.
The fact that a licence is legally possible does not mean that the business is automatically viable.
The commercial case must be demonstrated.
Nairobi has an unusual opportunity
The electricity sector is changing at precisely the moment when Nairobi has a reason to rethink its relationship with electricity. The Energy Act, 2019 established the statutory foundation for a more differentiated electricity market.
The 2024 Electricity Market, Bulk Supply and Open Access Regulations began translating that framework into practical mechanisms for bulk supply, open access, multiple suppliers and wheeling.
The 2026 regulations have now replaced that framework with a more developed market structure, including provisions that allow greater participation by generators, network service providers, retailers and eligible consumers.
At the same time, county governments have legal mechanisms for establishing commercially oriented county entities, while street lighting is already an expressly assigned county function under the Constitution’s Fourth Schedule.
Nairobi therefore has several pieces of the puzzle already in place. It has electricity demand. It has public infrastructure. It has an Energy and Lighting function. It has technical personnel. It has street lighting assets. It has large electricity-consuming facilities. It has a pressing need to control expenditure. And Kenya’s electricity market is gradually opening to new forms of procurement and supply.
The remaining question is whether the county is willing to think of electricity not simply as another bill to be paid, but as a strategic municipal service.
A city should know how it buys its electricity
Nairobi does not need to declare war on Kenya Power. It does not need to build a second national grid. It does not need to become an electricity generator overnight. It needs to start by asking a more modest question.
Can one of Africa’s largest cities become a better electricity buyer? If the answer is yes, the next question follows naturally. Can that buying power be turned into a professionally managed municipal electricity utility?
The initial customer would be Nairobi County itself.
The first objective would be to reduce and better manage the cost of electricity consumed by public facilities and infrastructure. The next step could be to develop distributed generation, storage and selected mini-grids.
After that, where the economics and regulation permit, the utility could offer electricity to businesses and residents who choose an alternative supplier.
Over time, Nairobi could move from being a large electricity customer to becoming an active participant in the electricity market.
The idea should not be judged by whether Nairobi can immediately compete with Kenya Power across the entire city.
It cannot.
Kenya Power’s network, customer base and institutional experience are far too extensive for that to be a realistic starting point.
The more useful question is whether Nairobi can establish a small, financially disciplined and technically competent electricity business and allow it to grow as the market develops.
The answer is worth investigating.
The electricity market is opening.
Nairobi is already a major consumer.
The county already has part of the technical machinery required to manage public lighting and energy infrastructure.
And the law provides mechanisms through which county governments can establish commercially oriented entities to deliver public services.
The opportunity may therefore be less about replacing Kenya Power than about changing Nairobi’s position within Kenya’s electricity system.
For decades, Nairobi has largely asked how much electricity it must pay for. Perhaps the next question should be how strategically it can buy it.
Could Nairobi County become Kenya’s next electricity utility?
-
Product on sale
 AWEBook Volume 2Original price was: KShs 3,500.00.KShs 3,000.00Current price is: KShs 3,000.00.